Trending requests

Log in

Warehousing & Logistics in The United Kingdom

Warehouse space, 3PL services and transport capacity across the UK. Tell us what you need and FLOX matches you with providers who have capacity now.

Free to enquire, no obligation

25Key Motorways
90%Population Reach

About The United Kingdom

The United Kingdom is one of the most developed logistics markets in Europe. Its backbone is an extensive and advanced road freight network.

National Highways manages approximately 4,566 miles of motorway and trunk road that carry roughly two-thirds of UK freight miles and from the Golden Triangle in the East and West Midlands around 85 to 90 percent of the UK population sits within a four-hour HGV drive (ONS 2022).

UK warehouse stock has roughly doubled in the past decade, driven by e-commerce, grocery, 3PL outsourcing and reshoring. Savills reports UK big-box take-up of 14.7 million sq ft in 2025, the strongest year in three, with vacancy expected to ease toward 7.4 percent by the end of 2026.

Cushman and Wakefield puts UK occupational demand at 37.4 million sq ft in 2025, 12 percent ahead of the five-year pre-pandemic average and reports a 32 percent year-on-year jump in deals above 500,000 sq ft, led by 3PLs and manufacturers.

Aerial view of a major United Kingdom logistics and warehousing hub with motorway access
Modern distribution centres in the UK Golden Triangle logistics corridor

The country is served by:

- Globally connected deep-water ports at Felixstowe, London Gateway, Southampton, Liverpool and Immingham.

- 12 Freeports spanning England, Scotland and Wales.

- High-volume air cargo through Heathrow and East Midlands Airport.

- A growing network of Strategic Rail Freight Interchanges including DIRFT, SEGRO East Midlands Gateway and iPort Doncaster.

FLOX brings this national market together across 16 regional hubs, giving occupiers and 3PLs a single view of capacity, capability and live availability.

Get warehousing and transport quotes across the UK

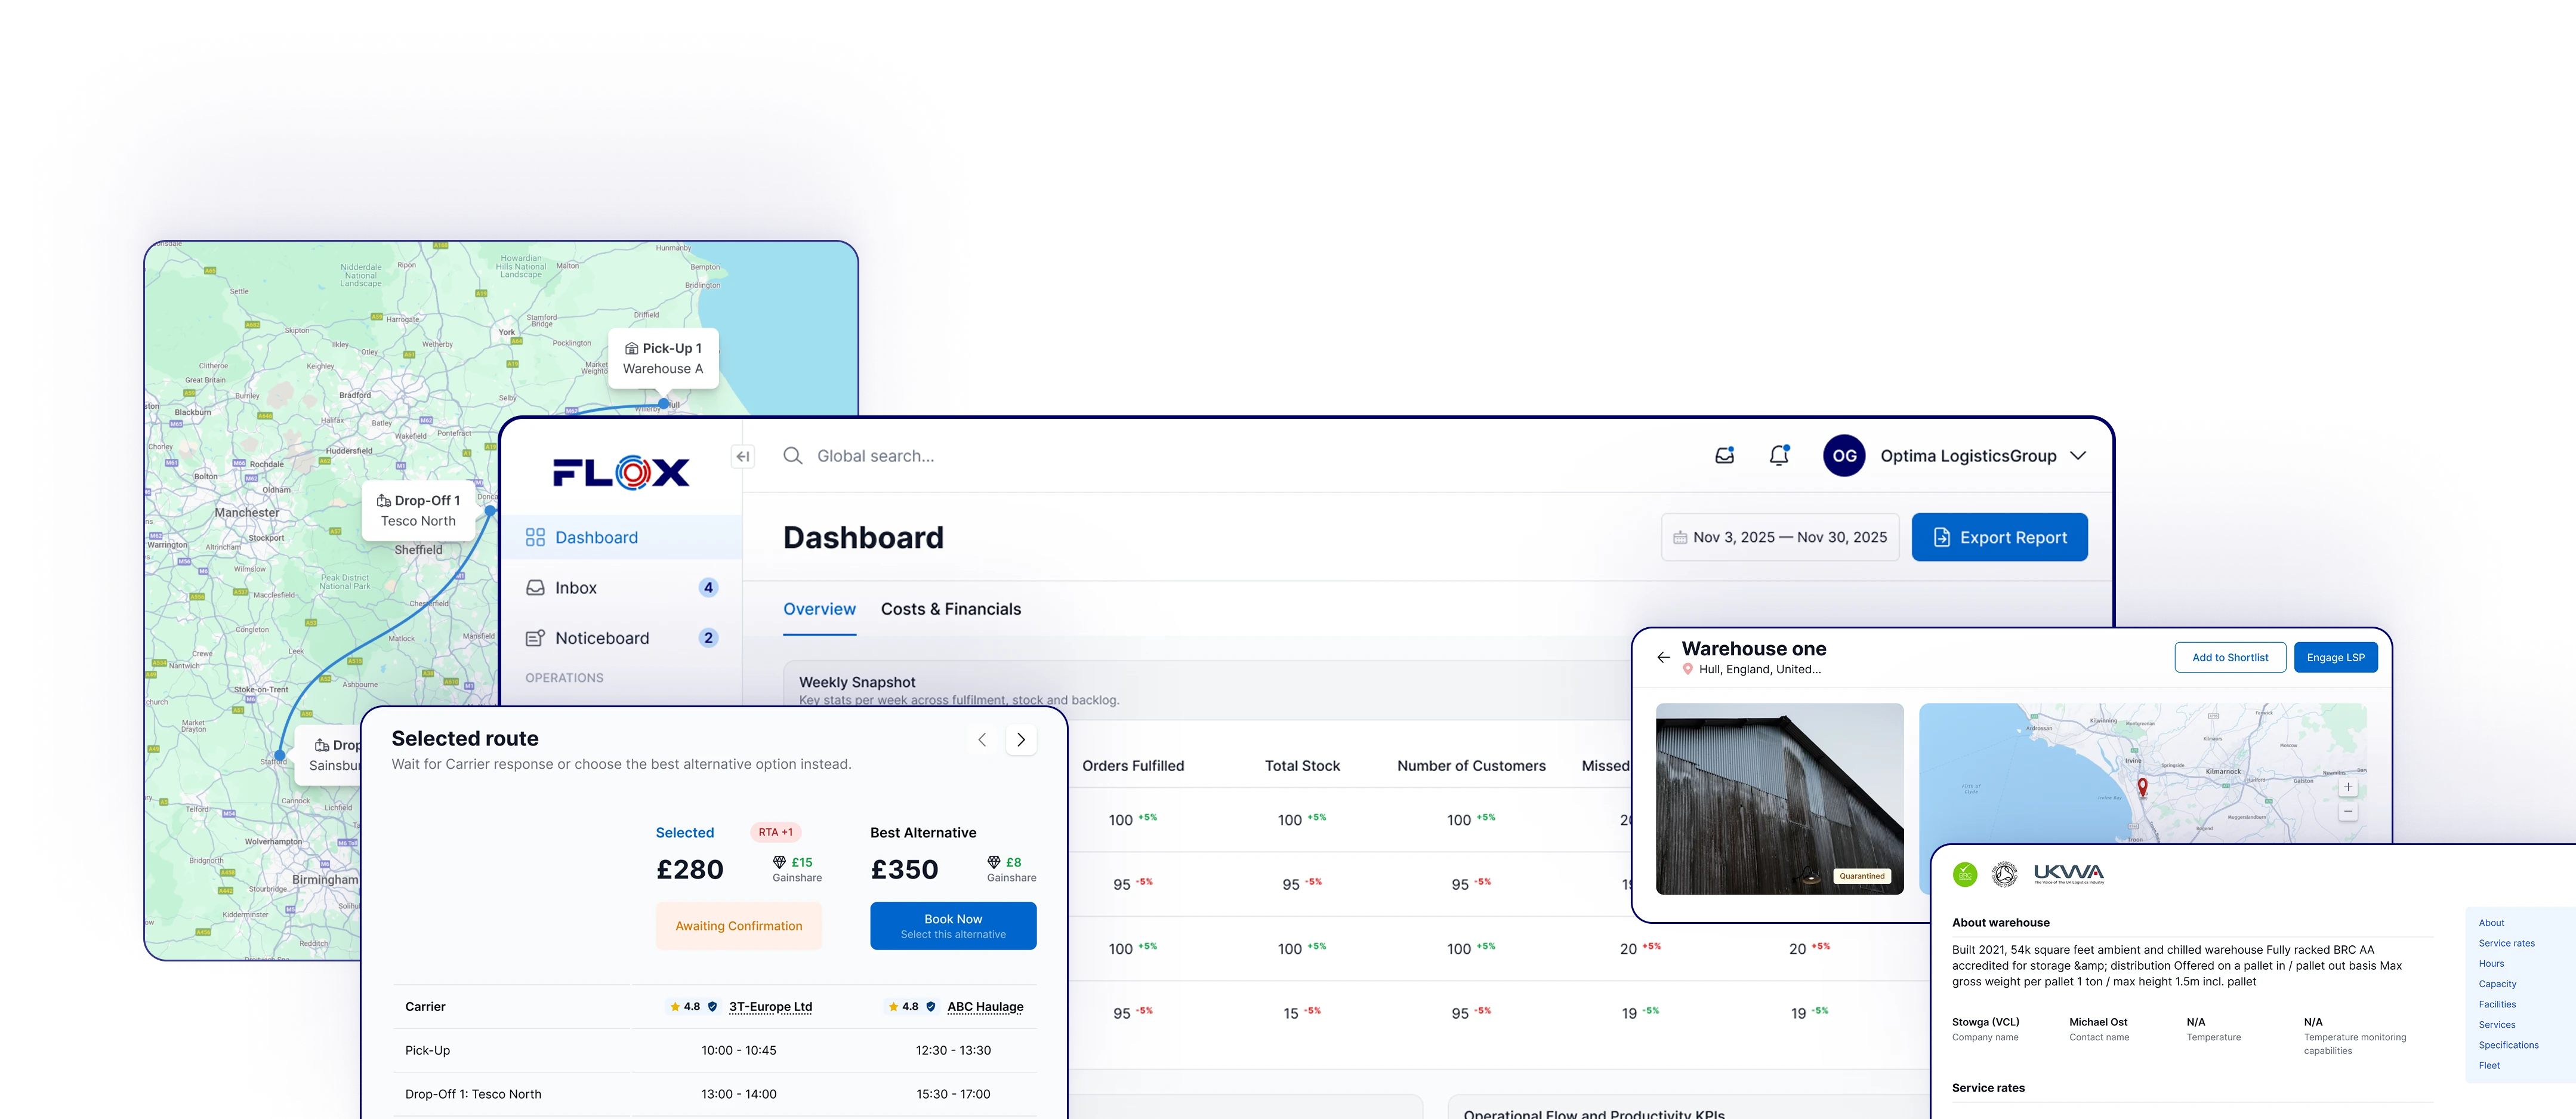
Holly, FLOX's AI assistant, asks a few questions about your goods, volumes and dates, then matches you with providers who have space or vehicles now. You see each provider's own rates plus FLOX's commission, compare the options side by side and book on FLOX's terms.

Why this region

The UK's extensive and advanced road freight network

The UK's extensive and advanced road freight network

Road freight carries roughly two-thirds of UK freight miles on National Highways' Strategic Road Network, a 4,566-mile mesh of motorways and major trunk roads built around a dense network of interchanges. Lorry traffic on the SRN totalled 10.2 billion vehicle miles in 2024 (DfT). The M1, M6, M40, M42 and M5 form the country's north-south spine through the Golden Triangle; the M25, M20 and M26 connect to Dover, the Channel Tunnel and Thames ports; the M62 and M18 run east-west across the industrial North; the M4 and M5 serve the South West and Wales. Smart-motorway operation across large sections of the M1, M3, M4, M6 and M25 has added lane capacity. For national distribution, the M1-M6 corridor still carries more UK logistics tonnage than any other route in the country.
World-class port infrastructure and deep-water capacity

World-class port infrastructure and deep-water capacity

UK ports handled 429.7 million tonnes in 2024 (DfT). Felixstowe is Britain's largest container port, with roughly 40 to 48 percent of containerised trade and about 3.0 million TEU a year. DP World London Gateway is the newest deep-water container port, extending its third berth and second on-site rail terminal, with 3.5 million TEU of planned capacity. Southampton serves the largest Asia vessels on the south coast. Liverpool's Liverpool2 terminal anchors west-coast container traffic. Immingham and the Humber is the UK's largest port by tonnage, driven by bulk, roll-on-roll-off and energy cargoes. Alongside those, Hull, Dover, Tilbury, Teesport and Grangemouth give the network continuous coverage and dual-coast resilience.
Growing rail freight and strategic multimodal interchanges

Growing rail freight and strategic multimodal interchanges

The United Kingdom has invested heavily in Strategic Rail Freight Interchanges. DIRFT (Daventry) is the highest-volume intermodal park in Europe; SEGRO East Midlands Gateway runs up to 16 trains per day of 775 metres; SEGRO Logistics Park Northampton has now tied into the West Coast Main Line via the Northampton Loop; iPort Doncaster doubled its rail capacity in autumn 2025; and consented schemes at West Midlands Interchange (M6 J12) and the planned East Midlands Interchange add further capacity. Rail freight removes HGVs from the SRN, cuts emissions and gives large occupiers a viable container route from Felixstowe, London Gateway and Southampton into the Midlands and the North. Maritime Transport, Freightliner, DB Cargo and GB Railfreight operate the majority of UK intermodal services.
Deep and diverse labour market across the four nations

Deep and diverse labour market across the four nations

With a resident population of approximately 69.3 million at mid-2024 (ONS), the UK offers a deep labour pool across every logistics discipline: warehouse operatives, HGV drivers, freight forwarders, engineers, data scientists and supply-chain leaders. The Midlands concentration of large-format logistics gives occupiers access to over a million workers inside a 30-minute drive of the core. London and the South East hold the densest pool of senior talent and supply-chain technology employers. The North, the Central Belt and South Wales combine manufacturing heritage with lower-cost labour. Apprenticeship and Skills Bootcamp funding, Freeport skills pots and regional devolution deals are broadening the talent supply across all four nations.
Freeport and investment incentives across 12 designated zones

Freeport and investment incentives across 12 designated zones

The UK Freeport programme now covers 12 designated zones. In England: East Midlands Airport, Felixstowe and Harwich, Humber, Liverpool City Region, Plymouth and South Devon, Solent, Teesside and Thames. In Scotland, the Inverness and Cromarty Firth and Firth of Forth Green Freeports. In Wales, Anglesey and Celtic. Freeport benefits include Customs Zone duty relief and suspension, enhanced capital allowances, Structures and Buildings Allowance, business rates relief, employer National Insurance contributions relief on eligible new hires and Stamp Duty Land Tax relief in designated tax sites. The UK Freeports Programme Report 2025 details occupier uptake and investment flows. East Midlands Freeport is the UK's only inland Freeport and anchors a customs zone around EMA, SEGRO EMG and Ratcliffe-on-Soar.

Logistics capacity availability

Overview of warehousing and transport capacity across the region

Warehouse market overview

Warehouse market overview

UK warehouse stock has roughly doubled in the past decade and national capacity sits at the highest level on record. Savills' Big Shed Briefing reports 2025 big-box take-up of 14.7 million sq ft, the strongest year in three. Cushman and Wakefield records UK occupational demand at 37.4 million sq ft in 2025, 12 percent ahead of the five-year pre-pandemic average, with vacancy declining in the large-format segment. The East Midlands alone holds over 130 million sq ft of warehouse inventory and has been the largest single region for UK take-up for several years. London and the South East command the highest rents and the tightest vacancy; the North West, Yorkshire and the North East offer the deepest availability and the lowest per-square-foot rents. Speculative construction is concentrated on Panattoni Park Swindon (7.2 million sq ft on the former Honda site, the UK's largest speculative scheme), Panattoni Park Avonmouth, Hinckley Park and West Midlands Interchange. Demand is weighted to 3PLs and manufacturers for 2025 and into 2026, reflecting a normalisation after the e-commerce surge. Regional variation remains the dominant story: a national 7 percent vacancy figure masks sub-5 percent availability in London, the Golden Triangle core and the M25.

New warehouse developments

New developments

Panattoni Park Swindon (7.2 million sq ft on the former Honda site) is the UK's largest speculative scheme. GXO Panattoni Park Avonmouth (885,000 sq ft) is the UK's largest ever speculative build-to-suit, occupied by GXO in May 2025. DIRFT is in its fourth phase of expansion. East Midlands Freeport tax-site plots at EMG and Ratcliffe-on-Soar are in active development. iPort Doncaster completed Phase 2 of its rail upgrade in autumn 2025, doubling capacity. West Midlands Interchange (M6 J12) has planning consent and will open phased from 2027. Port 2XL is building out a second container berth at the Port of Liverpool. London Gateway is adding its third deep-water berth and its second on-site rail terminal. Hinckley Park, Magna Park Milton Keynes and SEGRO Logistics Park Northampton all have active delivery through 2026.

Transport capacity

Transport capacity

The UK haulage market is served by a mix of global, national and regional carriers. Major operators include DHL Supply Chain, XPO Logistics, GXO, Kuehne+Nagel, Wincanton (now part of GXO), Maritime Transport, Palletways, Culina Group and Gregory Distribution. Pallet networks (Palletways, Pall-Ex, Fortec, Palletline and The Pallet Network) provide national coverage for SME and mid-market shippers. Road freight accounts for the dominant share of UK goods movement, with lorry traffic on the Strategic Road Network totalling 10.2 billion vehicle miles in 2024 (DfT). Driver supply tightened sharply after 2020 and has stabilised through higher pay, faster licensing and expanded apprenticeships. Rail freight offsets road volumes on the Midlands trunk corridors and is forecast to grow as SRFI capacity expands.

Specialist capabilities

E-commerce fulfilment, cold chain and temperature-controlled, pharmaceutical and healthcare logistics, automotive and JIT logistics, bonded and customs warehousing, Freeport customs zones, container drayage, hazardous goods, high-value and secure storage, reverse logistics and automation

FLOX in the UK

The network lists more than 1,100 warehouses across the UK, with providers in every UK region, and more than 3,000 worldwide. The figures on each regional page count the warehouses listed within 30 km of that region's centre.

Tell Holly what you need to store or move, where and when. FLOX matches your requirements with warehouse providers, 3PLs and carriers based on capability, capacity and location, helping you find suitable options and get quotes.

Book through FLOX and manage the work in one place, with warehouse storage available without a long lease. Enquiries are free, with no obligation to book.

Prefer a person? Tell us what you need and a FLOX specialist replies within a few working hours.
Alternative Transport Solutions
AMCO
Arrow XL
ASDA
Avon
Aztek Logistics
Bowker Group
CEVA Logistics
Cloud9 Fulfilment
Cool Stak
DFS Worldwide
Freight Logistics Solutions
Global Reach Logistics
Hallam Express
Hilti
Iris
JJX Logistics
Kays Logistics
Mercium
Miniclipper Logistics
NX
Optima
PAV Haulage
Seko
Smart Fulfilment
Smiths News
Thrive Fulfilment
Unipart
Verran Freight
WT Transport
Flex Technologies
Galliance
Hogback Distillery
MEH Pivara
Primary Pets
Ramtang Cello
Thortful
Yvonne Belhomme

FAQs

Answers to what buyers ask most about warehousing and logistics in the UK. Can't see your question? Check out our FAQs page or tell us what you need.

Read all FAQs
The Golden Triangle is the area broadly between the M1, M6 and M69 in the East and West Midlands, anchored by Magna Park (Lutterworth), DIRFT (Daventry) and SEGRO East Midlands Gateway. From this core, approximately 85 to 90 percent of the UK population sits within a four-hour HGV drive. That drivetime economics, combined with dense motorway access and SRFI rail, makes the Midlands the default national distribution location for large-format UK occupiers.
Felixstowe is the UK's largest container port, handling roughly 40 to 48 percent of Britain's containerised trade (around 3.0 million TEU in 2024). DP World London Gateway is the UK's newest deep-water container port with 3.5 million TEU of planned capacity. Southampton handles the largest Asia vessels on the south coast and Liverpool's Liverpool2 terminal anchors west-coast container trade. Immingham and the Humber is the UK's largest port by tonnage (DfT).
UK warehouse stock has roughly doubled in the past decade and now exceeds 700 million sq ft. The East Midlands alone holds over 130 million sq ft. Savills reports 2025 big-box take-up of 14.7 million sq ft and projects baseline vacancy of 7.4 percent by end-2026 (upside 6.5 percent). Cushman and Wakefield records 2025 UK occupational demand of 37.4 million sq ft, the strongest since 2022.
UK rail freight runs on a network of Strategic Rail Freight Interchanges (SRFIs), each sized at 60+ hectares and capable of handling four or more trains per day of up to 775 metres length. The main sites are DIRFT (Daventry), SEGRO East Midlands Gateway, SEGRO Logistics Park Northampton, Hams Hall (Birmingham), iPort Doncaster and London Gateway. Freightliner, DB Cargo, GB Railfreight and Maritime Transport run the bulk of UK intermodal services from the deep-sea ports into the Midlands and the North.
The UK has 12 designated Freeports. In England: East Midlands Airport, Felixstowe and Harwich, Humber, Liverpool City Region, Plymouth and South Devon, Solent, Teesside and Thames. In Scotland: the Inverness and Cromarty Firth and Firth of Forth Green Freeports. In Wales: Anglesey and Celtic. Benefits include Customs Zone duty suspension and relief, enhanced capital allowances, Structures and Buildings Allowance, business rates relief, employer NICs relief on eligible new hires and SDLT relief in tax sites (GOV.UK UK Freeports Programme Report 2025).
FLOX is the UK's logistics marketplace and orchestration platform. The marketplace layer lets occupiers and 3PLs search warehousing, transport and fulfilment providers across all 16 FLOX regions by location, service type, capacity and specialism. The orchestration layer then coordinates booking, contracting and ongoing flows across multi-site networks. Named 3PLs sit alongside anonymous regional SME providers and hauliers, giving both national scale and regional depth.

Time is priceless.
Sign up today.
FLOX Platform