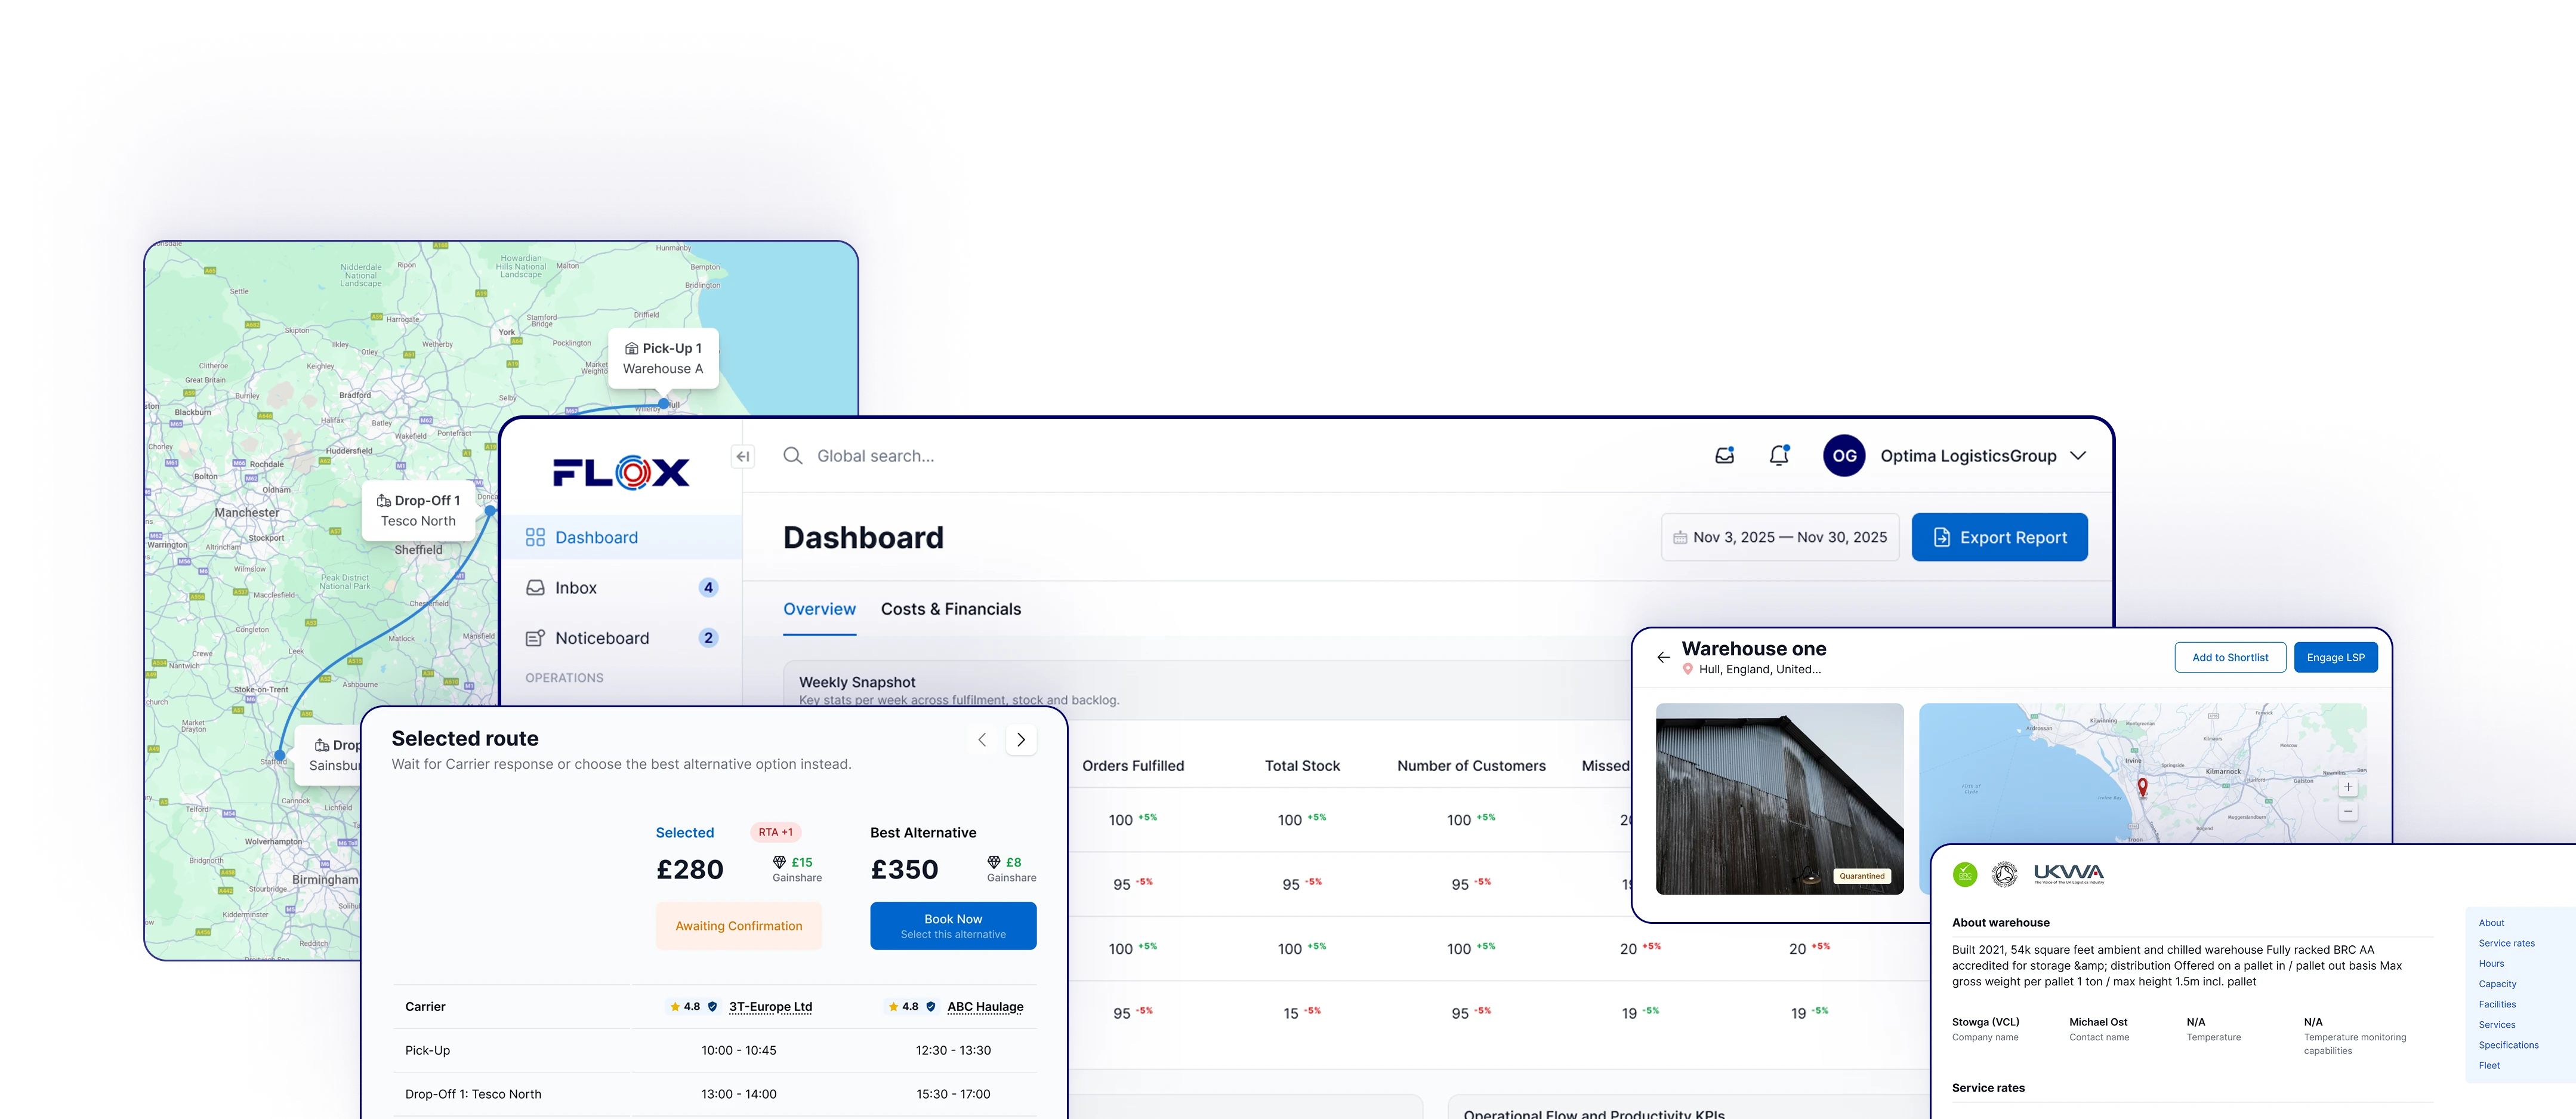
A Fibre2Fashion report on UK mid-market sentiment puts supply chain and energy costs firmly in the danger zone for the next six months. That finding is consistent across sectors: margin pressure arrives faster than the visibility needed to respond well.
The problem with reactive cost-cutting is that it treats all spend as equal. Carrier mix, warehousing footprint and inventory positioning each generate cost through different mechanisms. A blanket rate reduction or a dropped node can move the number on one line while inflating another. The saving shows up immediately; the exposure builds quietly.
Structured cost analysis starts with understanding where cost is actually created, not where it appears on an invoice. A firm consolidating warehouse nodes to cut rent may be lengthening inbound lead times in a way that forces higher safety stock elsewhere. The net position can be worse than the original.
Decision quality is not a luxury reserved for stable periods. It matters most precisely when margin is tightest and the temptation to move fast on incomplete data is strongest. Mid-market operators who build a clear picture of carrier mix, footprint trade-offs and inventory cost before cutting will take less ground back later.